Why central banks cannot always “look through” supply shocks
21.10.2026 11:00:00 EEST | Suomen Pankki | Blog
When inflation rises into the 5-6% range, firms may reprice more frequently just as households begin revising expectations more aggressively. These channels can reinforce one another, making early and credible policy action more valuable.
The euro area inflation surge of 2021-2024 surprised economists and policymakers alike. Inflation initially appeared to be a temporary consequence of energy prices, supply bottlenecks, and the reopening of economies after the pandemic. Yet the surge proved broader, more persistent, and more complex than standard macroeconomic models anticipated. The key question is not simply why inflation rose so much, but why it behaved so differently from previous episodes.
Our recent research suggests that the answer lies in the interaction of two nonlinear mechanisms that traditional models largely ignore: state-dependent pricing and inflation-expectation de-anchoring. Together, these mechanisms help explain why inflation accelerated rapidly once it reached certain levels, why it became more persistent than expected, and why delaying policy action can be costly.
Inflation changes behaviour when it becomes too large
Most macroeconomic models assume that the economy behaves similarly regardless of whether inflation is 2% or 8%. If a shock doubles in size, inflation roughly doubles as well. This assumption has served economists reasonably well during long periods of stable inflation.
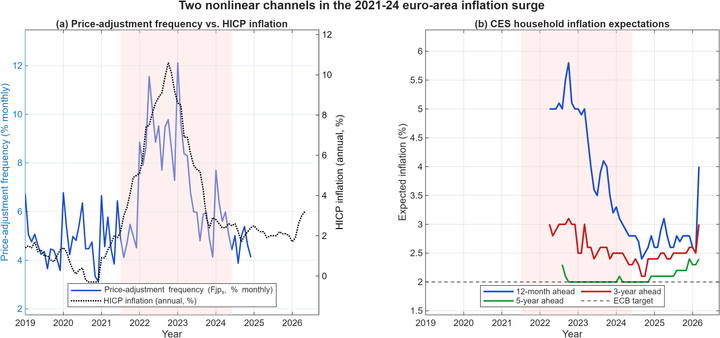
The recent euro area experience suggests that this linearity does not always hold. During the inflation surge, firms changed prices much more frequently than in normal times. At the same time, household inflation expectations became more sensitive to incoming inflation news. These changes in behavior activated once inflation crossed a critical threshold of roughly 5-6%.
Below the threshold, inflation behaves much as traditional models predict. Above it, pricing behaviour and expectations formation become more aggressive, amplifying the original disturbance. In other words, inflation dynamics becomes nonlinear.
State-dependent pricing: firms react more aggressively
Standard New Keynesian models often assume firms adjust prices according to fixed probabilities. Whether inflation is low or high, roughly the same fraction of firms update prices each period. The euro area data tell a different story. When inflation surged, firms became substantially more likely to adjust prices. This phenomenon, known as state-dependent pricing, means that inflation itself influences how often prices are reset. As inflation rises, firms update prices more frequently, making the economy more responsive to shocks.
Our estimated model captures this state-dependent mechanism by allowing the probability of price adjustment to increase with inflation. The result is a nonlinear Phillips curve: large shocks have disproportionately large effects on inflation. For small shocks, standard models and state-dependent pricing models generate almost identical results. For large shocks, the difference becomes substantial.
Expectations matter, but not all expectations
A second lesson concerns expectations. Professional forecasters‘ inflation expectations remained remarkably stable throughout the inflation surge. Our state-space estimation using the ECB Survey of Professional Forecasters indicates that professional inflation expectations stayed essentially anchored to the ECB inflation target of 2 percent.
Households behaved differently. When inflation exceeded approximately 5%, their expectations moved sharply higher. This is consistent with so called rational inattention: households devote limited attention to inflation when it remains low and close to target, but begin updating expectations more aggressively once inflation becomes unusually high.
De-anchoring matters primarily through forward-looking expectations rather than backward-looking indexation. Expectations influence current pricing decisions because firms incorporate anticipated future inflation into price-setting. When those expectations drift upward, inflation persistence increases.
The whole is larger than the sum of its parts
The most important result emerges when the two channels interact. When inflation rises, firms reprice more frequently. At the same time, households become more attentive and revise expectations upward. Higher expectations then influence firms’ pricing decisions, creating a feedback loop.
Our simulations show that the combined inflation effect exceeds the simple sum of the two individual effects. Economists call this super-additivity. The magnitude is modest in our baseline calibration but robust: higher realized inflation causes stronger expectation drift, which feeds back into future pricing decisions and generates additional persistence.
Why “looking through” inflation can be dangerous
Central banks often face supply shocks that temporarily raise inflation. In many circumstances, policymakers appropriately “look through” these shocks rather than respond aggressively. Our findings suggest caution when inflation approaches threshold levels.
Once inflation rises far above the target, say, into the 5-6% range, state-dependent pricing and expectation de-anchoring may activate simultaneously. The economy can enter a regime where inflation becomes increasingly self-reinforcing. Waiting for inflation to become persistent before responding may therefore be costly, because persistence is partly endogenous.
Our optimal policy exercises support this conclusion. The main gains do not come from surprising markets. They come from credible and anticipated policy reaction that prevent inflation from crossing the thresholds where firms and households change behaviour.
A broader lesson for monetary policy
The inflation surge of 2021-2024 may ultimately be remembered as a lesson in nonlinear economics. At low inflation, standard linear approximations work surprisingly well. At high inflation, firms alter pricing strategies, households pay closer attention, and inflation dynamics can change dramatically.
The euro area experience suggests that firms may increase repricing frequency at roughly the same inflation levels at which households begin de-anchoring expectations. That coincidence creates the conditions for amplification exactly when policymakers would most like to avoid it.
For central banks, the implication is clear: when inflation enters the danger zone, acting early and credibly is not merely about reducing inflation. It is about preventing the economy from transitioning into a regime where inflation becomes harder to control in the first place.
Contacts
Median palvelulinja / Medietjänst / Media Service
Tel:+358 9 183 2101media@bof.fiSubscribe to releases from Suomen Pankki
Subscribe to all the latest releases from Suomen Pankki by registering your e-mail address below. You can unsubscribe at any time.
Latest releases from Suomen Pankki
Kutsu medialle: Suomen Pankin julkinen kuuleminen eduskunnan talousvaliokunnassa 20.10. klo 12.0014.10.2026 14:00:00 EEST | Kutsu
Talousvaliokunta järjestää kansanedustajille ja medialle avoimen, Eduskunnan pankkivaltuuston kertomuksen 2025 käsittelyyn liittyvän julkisen kuulemisen tiistaina 20.10.2026 klo 12.00 Pikkuparlamentin auditoriossa (Arkadiankatu 3).
Centralbankskrediternas roll i styrningen av Eurosystemets räntor ökar när likviditeten minskar14.10.2026 11:02:29 EEST | Pressmeddelande
När affärsbankernas inlåning i centralbanken, dvs. centralbankslikviditeten, minskar, kommer styrningen av de korta penningmarknadsräntorna basera sig allt mer på en aktiv penningmarknad och Eurosystemets likviditetstillförande refinansieringstransaktioner. Beloppet av centralbanksinlåning minskar till följd av förfall av de värdepapper som Eurosystemet köpte under perioden med låg inflation och under coronapandemin.
Likviditeetin vähentyessä eurojärjestelmän luottojen rooli korkojen ohjauksessa kasvaa14.10.2026 11:02:29 EEST | Tiedote
Eurojärjestelmä ohjaa jatkossa lyhyitä rahamarkkinakorkoja aktiivisen rahamarkkinan ja keskuspankkiluottojen avulla, kun liikepankkien keskuspankkitalletusten määrä eli keskuspankkilikviditeetti vähenee. Talletusten määrä vähenee, kun eurojärjestelmän hitaan inflaation ja koronapandemian aikana ostamat arvopaperit erääntyvät.
Role of the Eurosystem’s refinancing operations in interest rate steering will grow as liquidity declines14.10.2026 11:02:29 EEST | Press release
As the volume of central bank liquidity declines, the Eurosystem will conduct its steering of short-term money market interest rates via an active money market and its refinancing operations. Central bank liquidity means central bank deposits held by commercial banks, i.e. central bank reserves. The amount of central bank reserves is declining as the debt securities purchased by the Eurosystem during the low inflation period and the COVID-19 pandemic mature.
Finlands Banks chefdirektör deltar i IMF:s årsmöten13.10.2026 13:00:00 EEST | Pressmeddelande
Finlands Banks chefdirektör Olli Rehn deltar i Internationella valutafondens (IMF) och Världsbankens gemensamma årsmöte i Bangkok den 16 oktober 2026. Chefdirektör Rehn företräder Finland i valutafondens styrelse.
In our pressroom you can read all our latest releases, find our press contacts, images, documents and other relevant information about us.
Visit our pressroom