Interest rates on household loans increased in May 2026
30.6.2026 10:00:00 EEST | Suomen Pankki | Press release
The majority of Finnish households’ bank loans are variable-rate loans. The increase in market interest rates has resulted in higher interest rates on both new and existing loans. In the early part of the year, households drew down more fixed-rate housing loans than before.
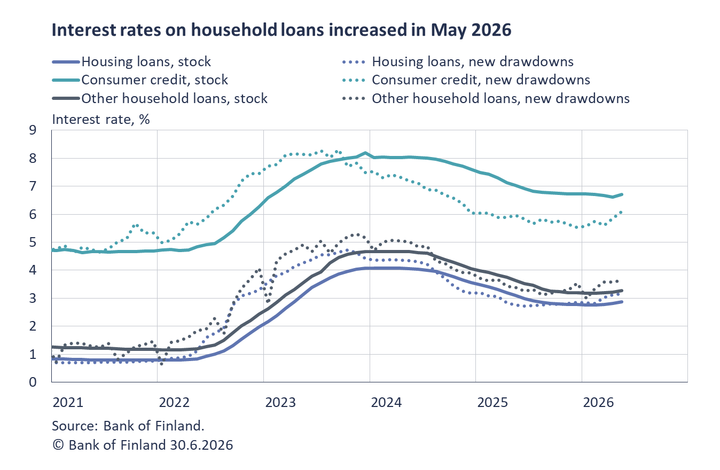
At the end of May 2026, Finnish households had EUR 140.6 billion in loans from banks operating in Finland. The average interest rate on the loan stock was 3.40%, having risen for three consecutive months. It was last higher than this in July 2025.
Higher market interest rates are reflected in the average interest rate on the loan stock. The increase in the average rate is due both to higher interest rates on new loans and to interest rate resets of existing variable-rate loans. In May 2026, the average interest rate on new household loan drawdowns 1 was 3.91%, which was 0,37 percentage points higher than in May 2025. At the end of May 2026, 89% of households’ bank loans were linked to Euribor rates. Nearly 3% were linked to banks’ own reference rates, while slightly over 7% were fixed-rate loans.
Within the housing loan stock, 95% of loans were linked to Euribor rates at the end of May 2026, while slightly less than 4% were fixed-rate loans. Buy-to-let mortgages are somewhat more often linked to Euribor rates than owner-occupied housing loans. Among owner-occupied housing loans, the shares of fixed-rate loans and loans linked to banks’ own reference rates are slightly higher than among buy-to-let mortgages. In January–May 2026, almost 6% of new housing loan drawdowns were fixed-rate loans. The share was last higher in the corresponding period (January–May) in 2013. The interest rate on new fixed-rate housing loans has also risen over the previous three months and was 3.64% in May 2026.
Consumer credit differs from other household loans in terms of interest rate linkage, as only 54% of consumer credit is linked to Euribor rates. This is mainly due to the large share of vehicle loans, most of which are fixed-rate loans. At the end of May 2026, the average interest rate on the stock of vehicle loans granted by banks was 4.40%, close to its lowest level in two years. The average interest rate on the stock of other consumer credit increased slightly from the previous month and stood at 7.66% in May. Increases in interest rates are reflected more quickly in new consumer credit drawdowns than in the loan stock. Nevertheless, interest rates on new loans remained below the average interest rate on the stock. In May 2026, the annualised agreed rate was 4.08% on new vehicle loans and7.64% on other consumer credit.
Loans
In May 2026, Finnish households drew down new housing loans totalling EUR 1.2 billion, which was EUR 100 million less than a year earlier. Of these drawdowns, buy-to-let mortgages accounted for EUR 110 million. The average interest rate on new housing loans rose from April to 3.17% in May. At the end of May 2026, the stock of housing loans stood at EUR 105.5 billion, and its annual growth rate was -0.1%. Buy-to-let mortgages accounted for EUR 9.2 billion of the housing loan stock. At the same time, Finnish households’ total loan stock included EUR 17.4 billion in consumer credit and EUR 17.7 billion in other loans.
In May 2026, Finnish non-financial corporations drew down new loans totalling EUR 2.3 billion. Of this amount, EUR 380 consisted of loans to housing corporations. The average interest rate on new corporate loan drawdowns decreased from April to 3.75%. At the end of May, the stock of loans to Finnish non-financial corporations stood at EUR 109.9 billion, of which loans to housing corporations accounted for EUR 46.3 billion.
Deposits
At the end of May 2026, Finnish households’ total deposit stock stood at EUR 118.0 billion, and the average interest rate on the deposit stock was 0.82%. Of the total, overnight deposits accounted for EUR 72.2 billion and deposits with an agreed maturity for EUR 16.6 billion. In May, Finnish households concluded new agreements on deposits with an agreed maturity to a value EUR 1.1 billion. The average interest rate on these new deposits was 2.48%.
For further information, please contact:
- Olli Tuomikoski, tel. +358 9 183 2925, email: olli.tuomikoski(at)bof.fi
- Markus Aaltonen, tel. +358 9 183 2395, email: markus.aaltonen(at)bof.fi
The next statistical release on money and banking statistics will be published at 10:00 on 28 July 2026.
Related statistical data and graphs are also available on the Bank of Finland website: https://www.suomenpankki.fi/en/statistics/.
The statistical data are also available via an API from the Bank of Finland’s open data portal. For details, see https://www.suomenpankki.fi/en/statistics/open-data/.
1 The figures for new loan drawdowns in this press release do not include overdrafts and credit card credit.
Links
Bank of Finland
The Bank of Finland is the national monetary authority and central bank of Finland. At the same time, it is also a part of the Eurosystem, which is responsible for monetary policy and other central bank tasks in the euro area and administers use of the world’s second largest currency – the euro.
Alternative languages
Subscribe to releases from Suomen Pankki
Subscribe to all the latest releases from Suomen Pankki by registering your e-mail address below. You can unsubscribe at any time.
Latest releases from Suomen Pankki
Why central banks cannot always “look through” supply shocks21.10.2026 11:00:00 EEST | Blog
When inflation rises into the 5-6% range, firms may reprice more frequently just as households begin revising expectations more aggressively. These channels can reinforce one another, making early and credible policy action more valuable.
Kutsu medialle: Suomen Pankin julkinen kuuleminen eduskunnan talousvaliokunnassa 20.10. klo 12.0014.10.2026 14:00:00 EEST | Kutsu
Talousvaliokunta järjestää kansanedustajille ja medialle avoimen, Eduskunnan pankkivaltuuston kertomuksen 2025 käsittelyyn liittyvän julkisen kuulemisen tiistaina 20.10.2026 klo 12.00 Pikkuparlamentin auditoriossa (Arkadiankatu 3).
Centralbankskrediternas roll i styrningen av Eurosystemets räntor ökar när likviditeten minskar14.10.2026 11:02:29 EEST | Pressmeddelande
När affärsbankernas inlåning i centralbanken, dvs. centralbankslikviditeten, minskar, kommer styrningen av de korta penningmarknadsräntorna basera sig allt mer på en aktiv penningmarknad och Eurosystemets likviditetstillförande refinansieringstransaktioner. Beloppet av centralbanksinlåning minskar till följd av förfall av de värdepapper som Eurosystemet köpte under perioden med låg inflation och under coronapandemin.
Likviditeetin vähentyessä eurojärjestelmän luottojen rooli korkojen ohjauksessa kasvaa14.10.2026 11:02:29 EEST | Tiedote
Eurojärjestelmä ohjaa jatkossa lyhyitä rahamarkkinakorkoja aktiivisen rahamarkkinan ja keskuspankkiluottojen avulla, kun liikepankkien keskuspankkitalletusten määrä eli keskuspankkilikviditeetti vähenee. Talletusten määrä vähenee, kun eurojärjestelmän hitaan inflaation ja koronapandemian aikana ostamat arvopaperit erääntyvät.
Role of the Eurosystem’s refinancing operations in interest rate steering will grow as liquidity declines14.10.2026 11:02:29 EEST | Press release
As the volume of central bank liquidity declines, the Eurosystem will conduct its steering of short-term money market interest rates via an active money market and its refinancing operations. Central bank liquidity means central bank deposits held by commercial banks, i.e. central bank reserves. The amount of central bank reserves is declining as the debt securities purchased by the Eurosystem during the low inflation period and the COVID-19 pandemic mature.
In our pressroom you can read all our latest releases, find our press contacts, images, documents and other relevant information about us.
Visit our pressroom